CoreWeave Shares Plunge as CEO Defends Debt-Fueled AI Expansion and $104 Billion Backlog
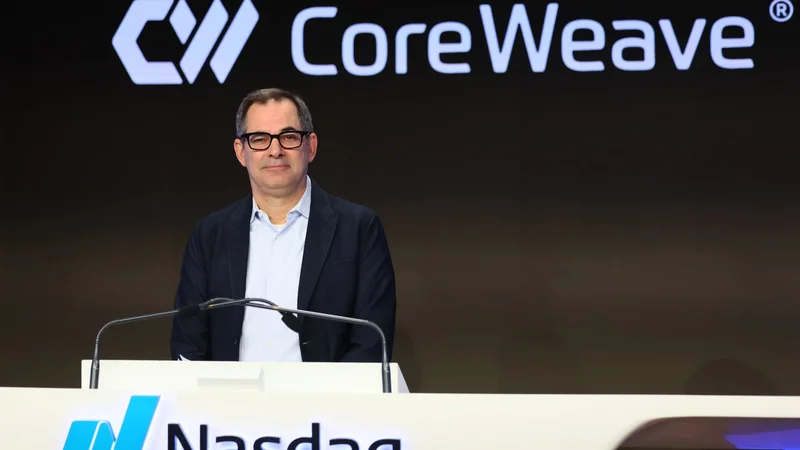
Image: Cnbc
Main Takeaway
CoreWeave shares fell as much as 18% while CEO Mike Intrator defended accelerated infrastructure spending, a $104 billion backlog, and the company’s debt-funded growth strategy.
Jump to Key PointsSummary
Shares fall as confidence holds
CoreWeave shares plunged between 13% and 18% in reported trading sessions as investors questioned the AI cloud provider’s profitability, financing needs, and expansion pace. CEO Mike Intrator responded by saying the market was acting irrationally and that he remained confident in the company’s business model, according to Bloomberg AI and Tradingview.
The selloff followed earnings-related concerns and renewed scrutiny of the company’s balance sheet. Coverage from CNBC, Bloomberg AI, and Tipranks tied the decline to investor unease over spending and profitability, while the Wall Street Journal framed the move within broader fears that enthusiasm for AI infrastructure has outrun fundamentals.
Debt fuels the expansion debate
CoreWeave’s central investor dispute is whether heavy borrowing is financing durable demand or amplifying downside risk. The company has accelerated its infrastructure buildout, a strategy Intrator defended during a CNBC interview after the post-earnings selloff. CoreWeave’s expansion requires substantial capital for data centers, servers, networking equipment, and power capacity.
Bond yields approaching 15% have intensified the concern, according to Roic, while market coverage has focused on debt-funded growth and narrowing confidence in the company’s ability to convert demand into earnings. Marketwise also pointed to weak earnings, shrinking margins, and insider selling as warning signs. These pressures explain why a business with a large contracted backlog can still face sharp equity and credit-market repricing.
The backlog behind management’s case
CoreWeave is defending its spending with a reported $104 billion revenue backlog, a figure cited by Roic and central to the bullish case presented in related investment analysis. The backlog indicates that customers have committed to significant future computing capacity, giving management a basis for arguing that new facilities are tied to contracted demand rather than speculative construction alone.
That argument depends on execution. Investors still have to assess delivery schedules, financing costs, customer concentration, hardware availability, and the margins attached to those commitments. Seekingalpha characterized the market’s reaction as excessive and highlighted another increase in capital-expenditure guidance, while CNBC’s account emphasized management’s deliberate decision to build capacity ahead of immediate profitability.
Insider sales add pressure
Insider transactions have made the selloff harder for CoreWeave to contain. Intellectia, citing Benzinga, reported that Intrator sold 32,455 Class A shares valued at $7.72 million on February 11. Marketwise separately highlighted sales by other senior executives, including the chief development officer and chief strategy officer.
Insider selling does not by itself establish that management expects a deterioration in operations, but it becomes a prominent market signal when a high-growth company is already facing debt and margin concerns. The transactions gave investors another reason to question leadership’s alignment with shareholders during a period of intense volatility. Coverage from CNBC, Intellectia, and Marketwise shows how the stock reaction combines operating concerns with credibility concerns around capital allocation and executive behavior.
AI infrastructure faces a valuation test
CoreWeave’s decline reflects a wider test for AI infrastructure companies. The business sits between cloud customers demanding large amounts of computing power and capital markets that are becoming less tolerant of long periods of spending before profits arrive. The Wall Street Journal linked CoreWeave’s fall to broader AI bubble fears, while Investing.com highlighted how Elon Musk’s “Yikes” reaction brought debt concerns into the public debate.
The result is a sharper distinction between demand and economics. Strong AI usage can support revenue growth, yet investors still need confidence that data-center assets will generate returns after interest expense, depreciation, and equipment commitments. Bloomberg AI’s account captured the tension: Intrator stands by the model, while both the shares and bonds have fallen under pressure.
What investors will watch next
CoreWeave’s next test is whether reported demand translates into revenue, cash flow, and improving margins while the company continues building capacity. Investors will focus on capital-expenditure guidance, financing terms, backlog conversion, customer commitments, and evidence that infrastructure spending produces acceptable returns.
Management’s confidence can steady employees and customers, but the stock’s recovery will depend on financial results rather than rhetoric. CoreWeave has presented its spending as an intentional response to demand, while the market has treated the pace as a balance-sheet risk. That disagreement will remain the defining issue until the company demonstrates that its backlog can support growth without imposing unsustainable borrowing costs.
Key Points
CoreWeave shares plunged up to 18% as investors challenged debt-funded expansion and profitability.
CEO Mike Intrator defended accelerated infrastructure spending and called the market reaction irrational.
CoreWeave’s $104 billion revenue backlog supports management’s case for continued AI capacity investment.
Bond yields nearing 15% intensified concerns about financing costs and balance-sheet risk.
Executive share sales added pressure as investors questioned management’s alignment with shareholders.
Questions Answered
CoreWeave shares fell because investors raised concerns about profitability, debt-funded infrastructure spending, rising financing costs, and executive share sales. The decline also reflected broader worries about excessive AI infrastructure valuations.
CoreWeave CEO Mike Intrator said the market was acting irrationally and defended the company’s business model. He argued that accelerated infrastructure spending reflects strong demand for AI computing capacity.
CoreWeave has a reported $104 billion revenue backlog, according to coverage cited in the article. Investors are watching whether the company can convert that backlog into revenue and cash flow after financing and operating costs.
CoreWeave’s debt is a concern because data-center expansion requires heavy borrowing while interest costs are rising. Reports cited bond yields approaching 15%, increasing pressure on margins and cash generation.
CoreWeave CEO Mike Intrator sold 32,455 Class A shares worth $7.72 million on February 11, according to coverage citing Benzinga. The transaction became a significant market signal amid the company’s stock decline and broader insider-selling concerns.
CoreWeave investors will watch backlog conversion, capital-expenditure guidance, financing terms, margins, and cash flow. The company needs to show that its AI infrastructure spending can produce sustainable returns while debt costs remain elevated.
Source Reliability
50% of sources are established · Avg reliability: 69
Go deeper with Organic Intel
Simple AI systems for your life, work, and business. Each one includes copyable prompts, guides, and downloadable resources.
Explore Systems