Bessent’s ‘I Am the House’ Bond Market Dare Collides With Rising Treasury Yields
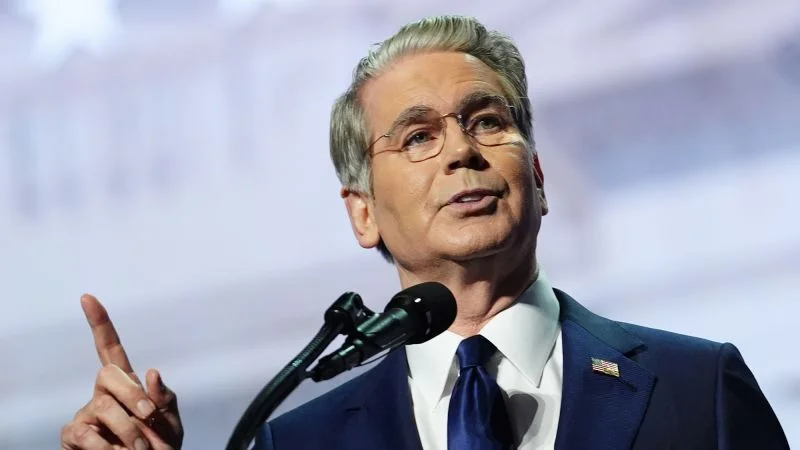
Image: Cnn
Main Takeaway
Treasury Secretary Scott Bessent’s bond-buying strategy failed to halt a sell-off that pushed 30-year Treasury yields to their highest level since 2002.
Jump to Key PointsSummary
The market rejects Bessent’s dare
Treasury Secretary Scott Bessent challenged investors to bet against the U.S. government’s ability to influence markets. Bond traders took the wager, selling longer-dated Treasurys and pushing yields sharply higher. The 30-year Treasury yield climbed from about 5.25% on Sept. 8 to 5.69% within three weeks, then closed at 5.62% on Sept. 30, the highest level since 2002.
Bessent’s remarks came during a speech at Southern Methodist University, where he said, “I am the house now,” while discussing Treasury intervention in currency and bond markets. His confidence reflected a career as a macro investor and his association with George Soros’s 1992 trade against the British pound. The bond market, however, treated the statement as a challenge rather than a signal of control.
Why long-term yields keep rising
Long-term Treasury yields are rising because investors are demanding more compensation for inflation, fiscal and supply risks, and uncertainty over future Federal Reserve policy. Oil prices, expectations for interest rates, and heavy corporate debt issuance have added pressure to the market, while concern over Washington’s borrowing needs has kept the sell-off focused on the long end.
The 10-year Treasury yield moved near 5.3%, while the 30-year yield remained around 5.6%. Those rates matter beyond bond trading because they influence mortgages, corporate borrowing, public-sector financing, and the government’s own interest bill. A higher long-term yield also signals that investors are questioning whether economic policy can stabilize debt without relying on continued borrowing.
Treasury’s buyback meets skepticism
Treasury’s bond-buyback program failed to produce the calming effect officials sought. The department announced the operation on Aug. 19 and later prepared to disclose its size, framing the effort as part of a broader strategy to support trading conditions and restrain longer-term yields. A reported $6 billion buyback drew little response from bond investors.
Buybacks can improve liquidity by removing older, less-traded securities from the market, but they don't erase the government’s overall financing needs. Treasury still has to issue debt, and investors can demand higher yields when they expect large supply, persistent deficits, or weaker fiscal discipline. The market’s reaction showed the limits of a technical intervention when investors are focused on the government’s balance sheet.
Credibility matters more than tactics
The central issue is credibility. A Treasury secretary can shape issuance, conduct buybacks, and coordinate with other officials, but those tools have limited power against investors who believe fiscal policy is unsustainable. Paul Krugman argued that boastful rhetoric can consume credibility that policymakers need when a genuine market intervention becomes necessary.
The bond market’s response also exposed a gap between control over market mechanics and control over the equilibrium price of debt. Bessent later said he couldn’t set that price, a more constrained description of Treasury’s role. Investors price the expected path of deficits, inflation, growth, and political decisions, all of which extend beyond the Treasury secretary’s direct authority.
The bill reaches households
Rising Treasury yields raise borrowing costs for households and businesses. Mortgage rates tend to track longer-term government debt, while corporate financing becomes more expensive when investors demand a higher risk-free return. The federal government also faces larger interest expenses as old debt matures and is refinanced at higher rates.
That pressure narrows Congress’s room to respond to economic weakness, because more tax revenue is directed toward interest payments. The debate is therefore shifting from whether Treasury can calm trading conditions to whether Congress can restore confidence through credible fiscal policy. One proposal discussed by Fortune calls for a fiscal commission with real authority, while broader analysis points to a sustainable debt path and limited room for tax increases without affecting the middle class.
What happens next
The next test is whether Treasury yields stabilize after the initial sell-off or continue climbing as investors reassess federal borrowing and inflation risks. Treasury can continue using buybacks and issuance management, but those measures address market plumbing rather than the deficit’s underlying trajectory.
Bessent’s experience gives him market knowledge and influence, yet the episode demonstrates that influence has boundaries. The government can intervene in specific markets, but it cannot simply order investors to accept a lower long-term borrowing cost. Durable relief requires confidence in fiscal decisions made by the administration and Congress, not another public dare to traders.
Key Points
Scott Bessent’s Treasury strategy failed to stop long-term yields from reaching multiyear highs.
The 30-year Treasury yield reached 5.69%, its highest level since 2002.
Treasury’s $6 billion bond buyback did little to calm investors focused on fiscal risks.
Rising government yields increase mortgage, corporate borrowing, and federal interest costs.
Congress faces pressure to restore fiscal credibility through credible debt and deficit policy.
Questions Answered
Scott Bessent said “I am the house now” to emphasize Treasury’s market knowledge and ability to intervene in currency and bond markets. He was challenging traders who might bet against the administration’s efforts to influence prices.
Scott Bessent’s bond-buying strategy did not lower long-term Treasury yields. The 30-year yield rose to 5.69% and later closed at 5.62%, despite Treasury’s buyback operation.
U.S. Treasury yields are rising because investors are pricing inflation, federal borrowing needs, debt supply, oil prices, and uncertainty over Federal Reserve policy. Concerns about fiscal credibility have added pressure to longer-term bonds.
Higher Treasury yields raise borrowing costs for households by influencing mortgage and other long-term loan rates. They also increase corporate financing costs and raise the federal government’s expense when debt is refinanced.
Scott Bessent can continue using buybacks and debt-management tools, but those measures won't resolve concerns about deficits and federal debt. Sustained relief depends on whether the administration and Congress produce a fiscal path investors consider credible.
Source Reliability
50% of sources are highly trusted · Avg reliability: 79
Go deeper with Organic Intel
Simple AI systems for your life, work, and business. Each one includes copyable prompts, guides, and downloadable resources.
Explore Systems